Building a Retirement Income Strategy That Connects Savings, Investments, and Lifestyle Goals
Retirement planning is about more than reaching a specific savings number. The transition from earning employment income to managing accumulated assets requires a thoughtful strategy that considers income needs, investments, taxes, healthcare, and personal goals.
During working years, financial decisions often focus on accumulation. Individuals contribute to retirement accounts, invest for growth, and build resources for the future. Once retirement begins, the focus changes from building wealth to managing it effectively.
A successful retirement income planning strategy helps connect savings, investments, income sources, and lifestyle expectations into a coordinated approach.
The goal is not only determining how much money is available.
The goal is creating a framework that helps those resources support a person’s desired lifestyle throughout retirement.
Quick Answer
Retirement income planning is the process of creating a strategy for using savings, investments, Social Security, pensions, and other financial resources to support expenses after leaving the workforce.
A complete retirement income strategy considers:
- Retirement expenses
- Income sources
- Investment allocation
- Withdrawal decisions
- Tax considerations
- Healthcare costs
- Inflation
- Market volatility
- Long-term goals
Unlike retirement saving, which focuses on accumulating assets, retirement income planning focuses on managing those assets throughout retirement.
Why Does Retirement Require a Different Financial Approach?
Retirement changes the role money plays in a person’s life.
Before retirement, income usually comes from employment, allowing individuals to continue saving and investing.
After retirement, accumulated assets often become the primary source of financial support.
This creates new challenges:
- Generating consistent income
- Protecting assets from unnecessary risk
- Managing withdrawals
- Maintaining purchasing power
- Planning for unexpected expenses
A portfolio strategy that works during the accumulation phase may require adjustments when it becomes responsible for funding everyday expenses.
What Is the Difference Between Retirement Saving and Retirement Income Planning?
Retirement Saving Focuses on Building Assets
During working years, individuals commonly focus on:
- Contributing to retirement accounts
- Increasing savings rates
- Investing for long-term growth
- Taking advantage of employer-sponsored plans
The main question is:
How much can be accumulated before retirement?
Retirement Income Planning Focuses on Distribution
After retirement, the questions become:
- How much income is needed?
- Which accounts should be used first?
- How should investments be managed?
- How can taxes be controlled?
- How can assets last throughout retirement?
The focus shifts from accumulation to sustainability.
Start With Defining Retirement Goals
Every retirement strategy should begin with understanding what retirement is expected to look like.
Important considerations include:
- Desired retirement age
- Housing plans
- Travel expectations
- Hobbies and activities
- Family responsibilities
- Charitable goals
- Lifestyle preferences
Retirement income needs are personal. Two people with similar savings may require very different strategies depending on their goals.
How Should Retirement Expenses Be Estimated?
Creating a realistic expense estimate is one of the foundations of retirement planning.
Essential Expenses
These may include:
- Housing
- Utilities
- Food
- Insurance
- Healthcare
Lifestyle Expenses
These may include:
- Travel
- Dining
- Recreation
- Entertainment
- Hobbies
Future Expenses
These may include:
- Long-term care
- Home modifications
- Family assistance
- Unexpected costs
Separating expenses into categories helps determine how much reliable income may be required.
Why Should Inflation Be Considered in Retirement Planning?
Retirement can last for decades, and expenses may increase over time.
Inflation can affect:
- Healthcare costs
- Housing
- Food
- Transportation
- Everyday services
A retirement strategy should consider whether income sources and investments can continue supporting purchasing power in the future.
Identify Retirement Income Sources
Retirement income may come from several sources, including:
- Social Security
- Pension benefits
- Retirement accounts
- Brokerage accounts
- Real estate income
- Business proceeds
Each source may have different characteristics related to:
- Reliability
- Tax treatment
- Growth potential
- Accessibility
The challenge is determining how these resources should work together.
Why Is Income Coordination Important?
Managing multiple income sources requires careful planning.
For example:
- Taking withdrawals from certain accounts may affect taxable income.
- Claiming benefits at different times may change future income.
- Investment decisions may affect long-term sustainability.
A coordinated approach evaluates how individual decisions affect the overall retirement strategy.
How Do Investments Support Retirement Income?
Investments continue to play an important role after retirement.
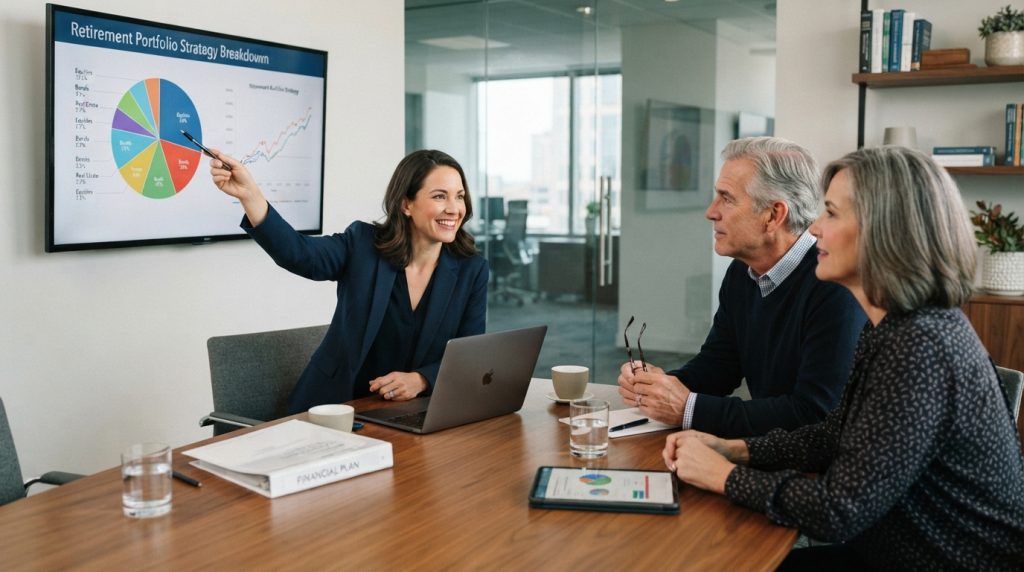
A retirement portfolio may need to provide:
- Income
- Growth potential
- Inflation protection
- Financial flexibility
Investment decisions should reflect:
- Retirement timeline
- Risk tolerance
- Income needs
- Personal financial goals
Why Is Asset Allocation Important During Retirement?
Asset allocation determines how investments are distributed among different asset categories.
Common categories include:
- Stocks
- Bonds
- Cash
- Other investment types
The SEC notes that diversification can help reduce risk by spreading investments across different assets, although it cannot eliminate losses completely.
A retirement portfolio typically needs a balance between growth and stability.
How Should Withdrawals Be Managed in Retirement?
Creating income from investments requires more than deciding how much to withdraw.
A withdrawal strategy should consider:
- Account types
- Tax impact
- Investment performance
- Future income needs
The order and timing of withdrawals can influence how long retirement assets may last.
Why Do Taxes Matter After Retirement?
Taxes remain an important part of retirement planning.
Potential taxable events include:
- Retirement account withdrawals
- Investment gains
- Required distributions
- Social Security taxation
A retirement strategy should consider both current and future tax implications.
How Can Tax Planning Improve Retirement Decisions?
Many retirement decisions have long-term consequences.
Examples include:
- Choosing which accounts to withdraw from
- Timing retirement income
- Evaluating Roth conversion opportunities
- Managing taxable income
Considering taxes as part of retirement planning can help create a more coordinated approach.
Social Security Decisions Require Careful Planning
Social Security is an important retirement income source for many individuals.
Factors that may influence claiming decisions include:
- Retirement age
- Health considerations
- Other income sources
- Spousal benefits
- Tax considerations
The right approach depends on personal circumstances.
Healthcare Costs Should Be Included in Retirement Planning
Healthcare is one of the largest uncertainties during retirement.
Planning considerations may include:
- Medicare premiums
- Supplemental coverage
- Prescription costs
- Long-term care needs
Ignoring healthcare expenses can create unexpected pressure on retirement assets.
How Does Market Volatility Affect Retirees?
Market changes are normal, but timing matters.
A market decline before retirement may allow time for recovery.
A market decline during retirement may create challenges because withdrawals may continue while investments have decreased in value.
This is often referred to as sequence-of-returns risk.
What Is Sequence-of-Returns Risk?
Sequence-of-returns risk describes how the timing of investment gains and losses can affect retirement outcomes.
Two retirees may have identical average returns but experience different results depending on when market changes occur.
Managing this risk may involve:
- Diversification
- Flexible spending
- Emergency reserves
- Income planning
Business Owners Have Additional Retirement Considerations
Business owners may have retirement assets connected to their company.
Planning considerations may include:
- Business value
- Succession planning
- Sale timing
- Income replacement
- Investment diversification
A business transition can significantly change a person’s financial picture.
Retirement Planning Should Include Legacy Goals
Many retirees want to preserve assets for:
- Children
- Grandchildren
- Charitable organizations
Legacy goals may influence:
- Withdrawal decisions
- Investment strategy
- Estate planning
A retirement strategy should consider both current needs and future intentions.
Retirement Income Planning Framework
Step 1: Define Retirement Goals
Identify:
- Desired lifestyle
- Retirement timeline
- Family priorities
Step 2: Review Current Resources
Evaluate:
- Savings
- Investments
- Retirement accounts
- Income sources
Step 3: Estimate Expenses
Calculate:
- Essential costs
- Lifestyle expenses
- Future needs
Step 4: Create Income Strategy
Review:
- Social Security
- Withdrawals
- Investment income
Step 5: Review Tax Impact
Consider:
- Account types
- Withdrawal timing
- Future tax obligations
Step 6: Manage Investment Risk
Evaluate:
- Asset allocation
- Diversification
- Liquidity
Step 7: Monitor and Adjust
Update the strategy as circumstances change.
Retirement Income Planning Checklist
Income
- Identify retirement income sources.
- Review Social Security options.
- Evaluate withdrawal needs.
Expenses
- Estimate retirement spending.
- Include healthcare costs.
- Plan for unexpected expenses.
Investments
- Review portfolio allocation.
- Maintain diversification.
- Evaluate risk level.
Taxes
- Review withdrawal strategies.
- Consider future tax impact.
- Coordinate retirement accounts.
Legacy
- Review beneficiaries.
- Update estate documents.
- Consider family goals.
Common Retirement Planning Mistakes
Focusing Only on Savings Amounts
A retirement balance does not automatically create a sustainable income strategy.
Ignoring Taxes
Tax decisions can affect how long retirement assets last.
Underestimating Healthcare Costs
Medical expenses can significantly affect retirement spending.
Taking Too Much Investment Risk
Excessive volatility may create unnecessary challenges.
Avoiding All Investment Risk
Insufficient growth may increase inflation concerns.
Failing to Update the Plan
Retirement strategies should change as circumstances evolve.
Frequently Asked Questions
What is retirement income planning?
Retirement income planning is the process of creating a strategy for using savings, investments, Social Security, pensions, and other resources to support financial needs after employment income ends.
When should retirement income planning begin?
Planning can begin years before retirement. Early preparation provides more time to evaluate savings, investments, income strategies, and potential risks.
How much income is needed in retirement?
The amount depends on lifestyle, expenses, healthcare needs, location, and personal goals. Retirement income needs vary from person to person.
Should investments change after retirement?
Many retirees adjust their investment strategy because their focus shifts from accumulation to income management and long-term sustainability.
How do taxes affect retirement income?
Taxes can influence withdrawal decisions, investment choices, and retirement account strategies. Coordinating tax considerations with retirement planning can improve long-term decision-making.
Final Thoughts
Retirement income planning is about creating a connection between accumulated assets and future lifestyle needs.
A successful strategy considers:
- Savings
- Investments
- Income sources
- Taxes
- Healthcare
- Personal goals
A comprehensive retirement income planning approach helps individuals understand how financial decisions work together throughout retirement.
Retirement is not a single financial event. It is a long-term stage of life that may change as markets, family circumstances, and personal priorities evolve.
By using thoughtful retirement planning strategies, individuals can create a framework designed around their unique goals and financial situation.
This article is intended for general educational purposes only. It does not provide individualized investment, tax, legal, accounting, insurance, retirement, or financial advice. Individuals should consult qualified professionals regarding their specific circumstances.